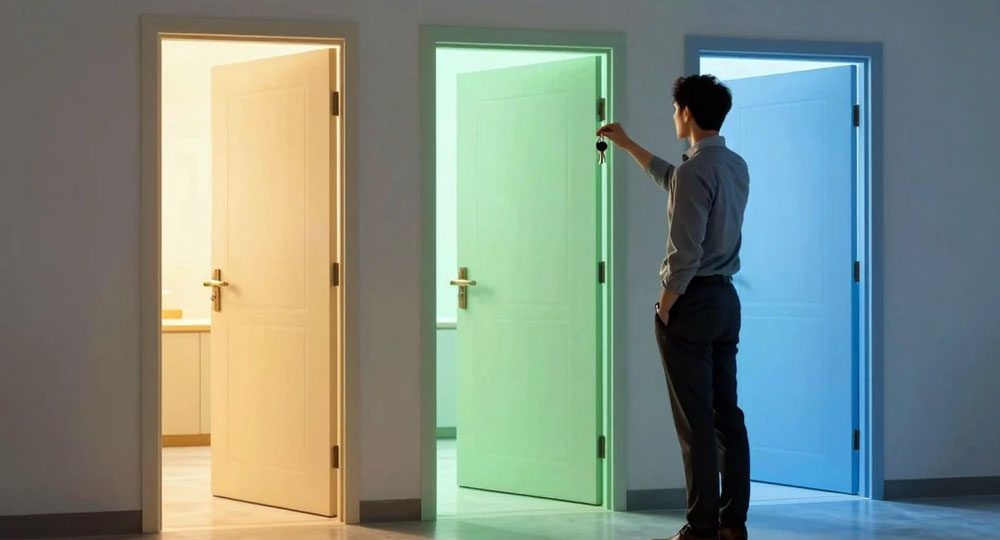
Three Doors, One Key: Your Practical Guide to Actually Accessing Capital
Key Takeaways
-
There are three distinct paths to funding right now: Alternative lenders (fastest), the Energy Bounce Back Scheme (cheapest), and government allocations (smallest). Knowing which one fits your business is half the battle.
-
Bank statements are the new collateral. Alternative lenders don’t care what you own; they care what moves through your account. Six months of clean, consistent banking history can unlock funding faster than owning a building.
-
The Energy Scheme is a loan guarantee, not a grant. It lowers your interest rate, but you still borrow from a commercial bank. You need tax clearance and accredited installer quotes before you knock.
-
R14,000 is real money—if you need the right thing. Government’s R2.5 billion allocation won’t buy a fleet of trucks. But it will buy a laptop, settle a month’s rent, or stock a shelf. Know what you’re asking for.
-
Timelines vary wildly: Days (alternative lenders) vs. weeks (Energy Scheme) vs. months (government allocations). Plan accordingly.
Let’s be honest: You’ve probably typed one of these phrases into Google lately.
“Alternatives to banks for small business loans.”
“How to apply for the Energy Bounce Back Scheme.”
“Is the R2.5 billion small business funding real?”
You’re not alone. These are the top funding questions South African entrepreneurs are asking right now. And behind each search is the same frustration: You know money exists. You just don’t know how to actually get it.
The banks say no. The government announces big numbers that never seem to reach your account. And the alternative lenders you hear about feel like a black box—do they fund businesses like yours, or just the shiny ones?
Here’s the truth: Capital is available. But it lives behind three different doors. Most owners knock on the wrong door, or they knock without the right key. This article is your map. By the end, you’ll know exactly which door is yours—and the specific step you need to take to walk through it.
Door 1: The Side Door (Alternatives to Banks)
The Google Query: “Alternatives to banks with strict requirements”
The Reality: You don’t need a perfect credit score or a bond over your mother’s house. You need proof that money moves through your business—consistently, predictably, and with discipline.
Alternative lenders (fintechs like Lula, Merchant Capital, Bridgement, and others) have fundamentally changed how funding is assessed. They use AI to scan your bank statements, not your balance sheet. They’re looking for revenue velocity, not collateral.
Who actually qualifies?
-
Registered businesses with at least 6–12 months of operational history
-
Monthly turnover of R10,000 or more (some have higher thresholds)
-
A business bank account that shows regular deposits (not just cash deposits once a month)
-
No major red flags like unpaid judgments or multiple overdraft busts
What do they offer?
-
Loan sizes: Typically R10,000 to R5 million, depending on your turnover
-
Repayment: Short-term (3–18 months), often deducted as a fixed percentage of your daily or weekly card sales
-
Speed: Decisions in hours, money in 24–48 hours
The exact steps to apply (today):
-
Log into your business banking app. Not your personal app—your business account.
-
Download the last 6–12 months of bank statements in PDF format. Make sure they’re clean (no unexplained cash deposits, no personal groceries mixed in).
-
Visit the website of a provider like Lula (www.lula.co.za), Merchant Capital (www.merchantcapital.co.za), or Bridgement (www.bridgement.co.za).
-
Click “Apply” and upload your statements. Most platforms also ask for your business registration number and ID.
-
Wait. You’ll typically get a decision within 24 hours. If approved, money lands in your account within two days.
The fine print (read this):
-
Interest rates are higher than banks. Expect anything from prime + 5% to prime + 15% . You’re paying for speed and accessibility.
-
Use this for short-term needs: Inventory, bridging a gap, covering salaries while waiting for a client to pay. Do not use this to buy long-term assets or consolidate debt.
-
If your statements are messy, fix that first. Funders are judging your financial discipline. Three months of clean banking before you apply can make a massive difference.
Estimated timeline: 2–5 days from application to funds in your account.
Door 2: The Green Door (Energy Bounce Back Scheme)
The Google Query: “How to access the Energy Bounce Back Loan Scheme”
The Reality: Government wants you off the grid. They’ve made it cheaper to borrow for solar by guaranteeing part of your loan to the bank. But you still have to apply—and you need to bring the right documents.
The Energy Bounce Back (EBB) scheme is a loan guarantee, not a grant. You borrow from a commercial bank (Standard Bank, Absa, FNB, Nedbank, and others). If you default, government covers a portion of the bank’s loss. That means the bank charges you lower interest than they would on an unsecured loan.
Who actually qualifies?
-
Registered SMEs with a valid SARS tax clearance certificate (no exceptions)
-
Using the funds for solar PV, inverters, batteries, or installation (not for operational costs or expansion)
-
Operating in South Africa with a viable business
What does it cover?
-
Solar panels
-
Inverters
-
Lithium-ion batteries
-
Installation costs (usually capped at a percentage of the total)
-
Not covered: Leased equipment, repairs to existing systems, or non-solar energy sources
The exact steps to apply:
-
Get three quotes from accredited solar installers. “Accredited” means registered with the relevant industry bodies (SABS, SolarGain, etc.) and capable of issuing a compliance certificate.
-
Visit your bank’s website and search for “Energy Bounce Back” or “EBB.” Each bank has a dedicated landing page with application forms.
-
Standard Bank: Look under Business Banking > Funding > EBB
-
Absa: Search “Energy Bounce Back” in the business section
-
FNB: Check Commercial Banking > Funding Solutions
-
Nedbank: Look for “Renewable Energy Funding”
-
-
Complete the application form. You’ll need:
-
Business registration documents
-
SARS tax clearance certificate
-
The three installer quotes
-
A motivation (why this investment makes sense for your business)
-
-
Submit and wait. Banks are processing these applications, but they’re swamped. Follow up.
-
If approved, install. You’ll need to use one of the quoted installers. Once installation is complete and signed off, the bank disburses funds.
The gotchas:
-
The scheme funds asset ownership, not leasing. If you were planning to lease solar (e.g., rent-to-own), this isn’t for you.
-
You need to own the property or have written permission from the landlord to install.
-
Interest rates are better than unsecured loans but still commercial. Expect prime + 2% to prime + 5%, depending on the bank and your risk profile.
Estimated timeline: 3–8 weeks from application to installation. The bank approval takes 2–4 weeks; installation adds another 1–2 weeks depending on installer availability.
Door 3: The Small Door (R2.5 Billion Allocation)
The Google Query: “Is R14,000 enough to help my business?”
The Reality: Government announced R2.5 billion for small businesses. Divided by the estimated number of SMMEs, it works out to roughly R14,000 per business. On paper, that feels insulting. In practice, it’s real money—if you need exactly what it offers.
The key is understanding that you’re not competing against every business in South Africa. You’re competing against businesses in your category, your province, your stage of formality. The money is distributed through agencies like SEFA (Small Enterprise Finance Agency), provincial development corporations, and accredited private funds.
Who actually gets this money?
-
Micro-businesses (spaza shops, hair salons, township manufacturers, street traders) are the priority
-
Informal and semi-formal businesses that can show some proof of operation
-
Survivalist enterprises (the smallest end of the spectrum) are explicitly targeted
If you’re a formal, registered SME with employees and a VAT number, you’re competing for a different pool—often through SEFA directly.
What does R14,000 actually buy?
-
A decent laptop and software for a freelancer
-
One month’s rent for a small shop
-
Stock for a spaza (cold drinks, bread, airtime, basic groceries)
-
A small marketing campaign
-
Registration fees, licences, or compliance costs
It does not buy: A delivery vehicle, a full solar system, multiple salaries, or expansion into a second branch.
The exact steps to find out if you qualify:
-
Go to the Department of Small Business Development website (www.dsbd.gov.za).
-
Look for the “Funding” or “Programmes” section. Find the list of “accredited partner funds” or “funding agencies.” This changes, so check regularly.
-
Identify agencies that match your province and sector. For example:
-
Gauteng: Gauteng Enterprise Propeller (GEP)
-
Western Cape: Department of Economic Development and Tourism (small business desk)
-
KZN: Ithala Development Finance Corporation
-
National: SEFA (for slightly larger, more formal SMEs)
-
-
Contact them directly. Ask: “What are your current application windows, and what criteria do you use?” Be polite, be persistent.
-
Apply when windows open. These are often short (two weeks or less). Have your documents ready: ID, business registration (if you have it), proof of address, bank statements, and a simple motivation.
The honest truth:
-
R14,000 won’t transform your business. But it might save it, or give it the tiny push it needs to get through a rough month.
-
The application process can be frustrating. There’s paperwork, there’s waiting, and there’s no guarantee.
-
But: If you’re a micro-business that banks ignore and alternative lenders find too small, this is your door.
Estimated timeline: 2–6 months from application to funds. Government moves slowly. Apply and forget—then be pleasantly surprised if it arrives.
| Door | Best For | Timeline | Interest Rate | First Step |
|---|---|---|---|---|
| Door 1: Side Door | Short-term cash needs (inventory, bridging) | 2–5 days | Prime +5% to +15% | Download 6 months of bank statements |
| Door 2: Green Door | Solar installation (own asset) | 3–8 weeks | Prime +2% to +5% | Get 3 accredited installer quotes |
| Door 3: Small Door | Micro-businesses, survivalist enterprises | 2–6 months | Often grant or low-interest loan | Visit DSBD website, find provincial agency |
Which Door Are You Knocking On?
Here’s a simple way to decide:
-
Need money this week for stock, salaries, or a supplier? → Door 1. Don’t wait for government. Go to an alternative lender.
-
Want to cut electricity costs permanently and own your backup power? → Door 2. Get those quotes and call your bank.
-
Running a micro-business that formal lenders ignore? → Door 3. It’s a long shot, but it’s your shot.
The Final Word
Capital isn’t hiding from you. It’s waiting behind the door you haven’t knocked on properly—or the one you gave up on too soon.
The difference between business owners who get funding and those who don’t isn’t luck. It’s clarity. Clarity about which door is theirs. Clarity about what documents to bring. Clarity about how long it will take.
Pick one door. Not all three. Just one.
Take the first step listed above. This week. Not when things get worse. Not when the invoice is 90 days overdue. Now.
Because the best time to find oxygen is before you’re gasping for air.
Disclaimer:
This article is for general informational and educational purposes only and does not constitute financial, legal, or professional advice. Interest rates, timelines, and application criteria change. You should verify current details with the relevant financial institution or government agency before applying. The estimated timelines provided are indicative only and come with no guarantee.
References
- South African Government. (2024). Energy Bounce Back Guarantee Scheme. [online] Available at: https://www.gov.za/EBB (Accessed March 2025).
- National Treasury. (2024). Budget Speech: Small Business Development Allocation. [online] Available at: https://www.treasury.gov.za (Accessed March 2025).
- Lula. (2025). Business Funding for South African SMEs. [online] Available at: https://www.lula.co.za (Accessed March 2025).
- Small Enterprise Finance Agency (SEFA). (2024). Annual Report and Funding Criteria. [online] Available at: https://www.sefa.org.za (Accessed March 2025).
- Merchant Capital. (2025). How Revenue-Based Financing Works. [online] Available at: https://www.merchantcapital.co.za (Accessed March 2025).